Wealth management for retirement · Geneva

Will your money last until 95?

Most people plan their retirement to age 85. It is the most expensive arithmetic mistake of their lives: in the EU, men draw their pension for a little over 18 years on average and women for almost 22, many for much longer. And the state pension replaces only part of the last income. This is not just about the wealthy, but about everyone who saves for retirement.

We run the numbers with you in two minutes. And we show you what your bank and your robo-advisor do not: the return your capital needs to last to 95, and how to get there.

A couple working out their retirement at the kitchen table

The calculation everyone should do once. Preferably before the decision.

Licensed by FINMASupervised by OSFINcontrol AG
In Geneva since 2002Founder-led, independent
Your portfolio, your nameSwissquote, Safra Sarasin, LLB, V-Bank
From €100,000Investable assets
The problem

The state pension covers about half. Your capital has to do the rest.

At retirement a large part of income falls away. Only capital that works closes the gap. And the bank account pays on average less than the ECB's inflation target.

2.50%ECB deposit facility rate, since September 2026
approx. 50%of the last gross salary is replaced by the mandatory pension, OECD average
18 to 22yearsis how long men and women in the EU draw a pension on average
up to 8%coupon on carefully selected corporate bonds in euros and dollars

On the account, capital loses purchasing power every year: overnight deposits of households in the euro area paid 0.29 percent on average in August 2026. Anyone who has worked for 40 years should not have to start calculating again at 75. That is why we do the numbers beforehand, with you.

At the same time the market pays interest again: the ECB raised its key rate twice in 2026, government bonds yield again, and carefully selected corporate bonds in euros and dollars pay up to 8 percent.

Sources: ECB, key rates and interest rate statistics August 2026; OECD, Pensions at a Glance 2025; Eurostat and OECD, years in retirement 2024; Genève Invest, market outlook second half of 2026. Pension levels depend on country and career.

What money earns today

Percent per year, indicative values October 2026
Account EUR, euro area averageapprox. 0.3Term deposit 1 year, averageapprox. 2.1German Bund 10 yearsapprox. 3.5France 10 yearsapprox. 5 Corporate bondsEUR/USD, selected6 to 8 Sources: ECB (August 2026), Deutsche Bundesbank, Genève Invest bond universe, as of October 2026. Coupon is not yield. Foreign currencies carry exchange rate risk.
Step 1 · Retirement check

Will your money last to 95? Run the numbers while you can still change something.

Eight inputs, two minutes. You see the result immediately, without signing up. Your personal Plan 95 shows the return your capital needs to last to 95 and how to get there: leverage calculation and a conversation with an adviser in your language. Free of charge.

Simplified calculation: need and pensions rise with inflation, no taxes on income, no fees, no home ownership. Pensions are calculated for life, capital until it runs out. The result is your calculation, not advice.

By this calculation your money lasts

Your assumptions: Adjust assumptions

The lever: how long your money lasts, depending on return

Capital sitting in an account or in the bank's standard products delivers the first line. The third line comes from a portfolio built for return that also has three protection mechanisms. What that looks like is right below this calculation. Here is the solution

Your Plan 95

Everything you need to get to 95. Free of charge.

  1. 1The leverage calculationImmediately after sending, at the top of this page: the return your capital needs to last to 95.
  2. 2The conversation30 minutes with an adviser in your language, with your pension statement, by phone or video. We also clarify how we can look after you in your country of residence.

For people with investable assets from €100,000.

By submitting you agree that Genève Invest Sàrl contacts you by email and phone. Details in the client information on data protection.

The solution

How your money gets to 95: strong returns, with three protection mechanisms.

Return without protection is speculation. Protection without return is the savings account. A Genève Invest portfolio combines both, not through products but through three rules we have applied to every single position since 2002.

1

Quality with a moat

We buy only companies with high returns on capital, pricing power and a business model competitors cannot easily copy. Such companies hold their value because they earn money even in bad years. That protects the value of your portfolio.

2

Bought at a discount to intrinsic value

Following the value principle, we buy quality only when the price is below what the company is worth. That discount is your margin of safety: it protects the entry when the market falls, and it is why we buy in crises when others sell.

3

Bonds with a predictable coupon

With a bond you know on the day you buy what interest you receive each year and when the capital comes back. Carefully selected corporate bonds in euros and dollars pay up to 8 percent. You can plan with that income: it arrives whether the stock market rises or falls, and the bond matures.

Two truths about money

Money has to work. And a small edge becomes enormous over the years.

Two sliders, two calculations. The first shows what your capital becomes depending on where it sits. The second shows what a small extra return from value investing adds up to over time.

Truth 1

Money has to work efficiently in equities and bonds. Over time the differences are enormous.

Truth 2

A small outperformance through value investing makes a huge difference over long periods.

Simplified compound interest calculation, nominal, before costs and taxes, without fluctuations. Account rate: ECB, overnight deposits of households in the euro area, August 2026. The equity return of 7 percent a year is an assumption, not a forecast. Coupons are not a portfolio return; foreign currencies carry currency risk. Outperformance through value investing is a goal of Genève Invest, not a commitment; active management can also lag the market. Buffett figures: Berkshire Hathaway, shareholder letter 2024. The past is not a reliable indicator of the future.

The result

Clearly higher, predictable income than in an account or an index fund, in a portfolio whose positions you can see and understand at any time. This is exactly the calculation we run in Plan 95 for your numbers.

Request my Plan 95

Bonds and equities are subject to price, credit and currency risk. Interest refers to the coupon at purchase, not the portfolio return. Outperformance is a goal, not a commitment.

The plan

Three steps. Your money always stays in your name.

1

Retirement check

At the top of this page, two minutes. You then know how large your gap is and how long your capital lasts. On request you receive your calculation as a personal report.

2

Analysis with two calculations

30 minutes, by phone or video. We calculate your situation in euros: need, pensions, capital and the return it takes.

3

Your portfolio, built bespoke

You choose your custodian bank: Swissquote, Safra Sarasin, LLB or, from January 2027, V-Bank, at terms Genève Invest has negotiated for its clients. We build your portfolio from individual securities and manage it under a power of attorney.

YouOwner, full control Your custodian bank of choiceSwissquote, Safra Sarasin,LLB, V-Bank (2027)Account and portfolio in your name Genève InvestPower of attorney DepositOrders Withdrawals go only to you. We cannot take money out. We earn when you earn.
Why bespoke

Wealth management built for you. Not off the rack.

The four strategies you see further down are groups in which we pool similar mandates. Your portfolio is none of them. It is built from individual securities and tailored to your needs: your gap, your horizon, your taxes, your currency.

1

Individual securities, not products

We buy individual bonds and equities for you that we have analysed ourselves. No in-house funds, no certificates, no products that earn someone else a margin. You see every position in your portfolio.

2

Goal: beat the index

Our ambition is a systematic outperformance of the relevant indices through focused value investing: stock picking and bond picking on value principles. Quality at a reasonable price, bought when others sell.

3

Active, not passive

Whoever invests in index funds carries the full market risk and cannot beat the market. We manage risk actively: securing gains, adjusting positions, staying able to act in a crisis. That is the decisive difference.

Outperformance is a goal, not a promise. Active management can also fall behind the market in individual years. Past performance is not a reliable indicator of future results.

Step 3 · Two engines

Income from bonds. Growth from quality equities.

A retirement portfolio needs both: an engine that delivers money every month and one that grows the capital over 20 years. How you weight them is decided by your figures from the check.

Engine 1 · Income

Bonds in euros and dollars, carefully selected

Our core business for more than 20 years: bonds of solid companies we have known for years, with running interest of up to 8 percent in euros and dollars. No certificates, no structured products, individual securities in your portfolio.

  • Selected by experts who examine every issuer individually
  • Coupons flow to your account, the capital stays invested
  • In euros or dollars, foreign currency only as a deliberate decision

Bonds are subject to interest rate, credit and currency risks. The rate shown is the running coupon, not the return of your portfolio.

Engine 2 · Growth

Quality equities, Europe and international

Companies with high return on capital, growing sales and pricing power, selected according to the Genève Invest approach and bought when the price is right. The core in Europe, complemented by international quality companies.

  • European stocks at the core: income and prices in euros
  • How capital gains, interest and dividends are taxed depends on your country of residence
  • Quality first, valuation second, fashions never

Equities fluctuate more than bonds. Tax treatment depends on your personal circumstances.

Euro and dollar, calculated openly

Some of the most solid bonds are denominated in dollars. For an investor who thinks in euros, that brings currency risk. We do not decide this in passing but with you: how large the dollar share may be and what it earns compared with euro bonds. We calculate both for you.

Bonds in foreign currency carry currency risk. The coupon is not the return of your portfolio.

Evidence

Four strategy groups. All figures published, all externally audited.

Annualised performance 2023 to 2025, calculated in euros, net of costs, before taxes. Each group pools individually managed mandates with a similar orientation. The performance report was audited by BDO AG under ISAE 3000.

Income portfolio+5.0%p.a. in euros · bond focus
Income plus return+8.1%p.a. in euros · bonds with equity share
Balanced portfolio+14.2%p.a. in euros · balanced
Dynamic portfolio+19.6%p.a. in euros · equity focus

Past performance is not a reliable indicator of future results. Higher returns come with higher fluctuations. All values are calculated in euros. Source: Genève Invest Sàrl, performance report as of 31.12.2025.

In a higher interest rate environment we see above all the lower price at which quality can currently be bought.Genève Invest, Capital Market Outlook H2 2026
Library

Three documents to read before you retire.

Free of charge, in your inbox within minutes. You will find all documents on a separate page.

Market outlook

Outlook H2 2026: AI euphoria and the rate dilemma

Because you are invested and need to know whether rates keep rising, the AI rally turns and bond markets hold. Before the market shows you.

Rates, bonds, equities, currencies, commodities: three scenarios, clear positions and the places where we were right too early.

32 pages · second half of 2026Request
Insights 07

Building a bond portfolio

Because a portfolio that considers only three of the four pillars is a pseudo-security that collapses under stress.

The four pillars of a robust income portfolio: issuers, sectors, maturities, rating classes.

12 pages · May 2026 · in GermanRequest
Insights 02

Bonds vs equities

Because the question bonds or equities is the wrong question, and after twelve pages you will ask the right one.

Opportunities and risks compared: income mechanics, capital protection, volatility, and why the answer is usually a mix.

12 pages · April 2026 · in GermanRequest

Advertisement. The documents name no individual securities as recommendations and do not replace personal advice.

All documents in the library
Portfolio review

What is going wrong in your portfolio, we see in 20 minutes. So will you.

Banks park client money in their own funds. Robo-advisors buy index ETFs and let you carry the full market risk. And private investors have repeated the same seven mistakes for decades. Send us your portfolio statement and we show you what is costing you return and what you can do about it. Free, in your language, no obligation.

How the review works

You send us your current portfolio statement (a PDF is enough). Within five working days you receive a written assessment of risk, costs, quality of positions and gaps, plus a conversation with an adviser in your language who goes through the points with you. What you do afterwards is your decision.

Request the reviewFor portfolios from €100,000.

The review is an assessment based on the documents submitted and does not replace comprehensive advice. Advertising.

Self-test

Tick what applies to your portfolio

The seven mistakes we find most often

Have these points reviewed
Comparison

Your bank, a robo-advisor or Genève Invest? The table your bank does not show you.

CriterionBankRobo-advisorGenève Invest
What sits in the portfolioIn-house funds and products that often lag the marketThe provider's index ETFsIndividual bonds and equities, chosen on the market and analysed by us
GoalPlacing productsMarket return minus costsSystematic outperformance of the relevant indices through value investing
Active managementLimited, following the house viewNone; full market risk, no chance of excess returnActive management of risk and positions, stock and bond picking
IndividualityStandard profilesQuestionnaire, risk classTailored to your gap, your horizon, your taxes and your currency
Total costsSeveral line items, retrocessionsETF fees plus robo fee, often 1 to 2 percent in total, without added valueSmall, transparent base fee plus a results-based performance fee with high-water mark; everything on the custody statement
TerminationDepending on contractAny timeAt the end of each quarter, no minimum term
Contact personChanges regularlyChat or hotlineOne person in Geneva who manages your portfolio

Simplified comparison of typical models, no statement about individual providers. Outperformance is a goal, not a promise.

Who looks after your money

Five people. Four languages. One person responsible for you.

Specialised since 2002 in high-income corporate bonds and value equities. You do not talk to a hotline but to the person who manages your portfolio, in your language, and who runs the numbers every week with people approaching retirement.

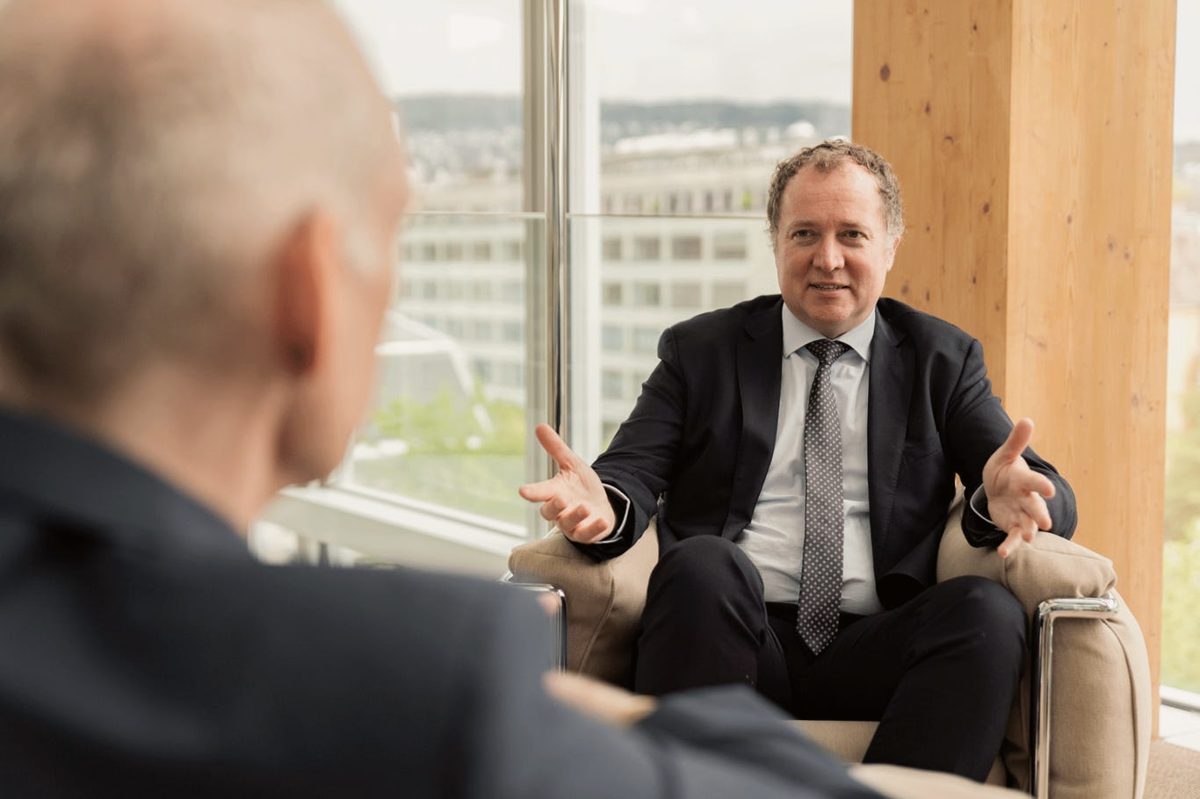
Helge Müller in conversation with a client at the Genève Invest offices in Geneva

Helge Müller in a client meeting, Geneva.

The stock market is keeping your nerve where others lose theirs.Erhard Blanck, quoted in the Capital Market Outlook H2 2026
Your contacts in English
Helge Müller
Helge MüllerFounder, managing director and portfolio manager · GermanLanguages: DE, FR, EN, ES, PTSince 2002 I have been working out with people how far their money will go. The answer is in the figures, not in the brochure.+41 22 716 43 55
Romain Daudey
Romain DaudeyManaging director and client adviser · FrenchLanguages: FR, ENI run Genève Invest and look after French-speaking clients myself. Whoever entrusts us with their money knows who decides.+41 22 716 43 55

An adviser in your language calls you back within one working day.

The whole team by language

German

Helge Müller
Helge Müller
Founder, managing director and portfolio manager · DE, FR, EN, ES, PT
Stephanie Roderburg
Stephanie Roderburg
Portfolio manager · DE, FR, EN

French

Romain Daudey
Romain Daudey
Managing director and client adviser · FR, EN
Anthony Koyomian
Anthony Koyomian
Client relationship manager and portfolio manager · FR, EN

Italian

Giacomo Iezzi
Giacomo Iezzi
Portfolio manager, Italian-speaking clients · IT, EN
Frequently asked questions
Is my state pension enough?

For most people, not on its own. On the OECD average, the mandatory pension replaces about half of the last gross salary, in many countries less. The check above shows how large your gap is; in the conversation we calculate it precisely with your pension statement.

What does asset management cost?

A small, transparent base fee as a percentage of assets under management plus a results-based performance fee, always on a high-water mark basis: we participate again only once your portfolio has exceeded its previous high. Everything is on your custody statement. The exact rates and a cost statement are provided before you sign.

What sets you apart from a robo-advisor?

A robo-advisor invests in index funds. You therefore carry the full market risk, outperformance is ruled out, and total costs from ETF fees and the robo fee often reach 1 to 2 percent. We build your portfolio from individual securities, manage risk actively and aim to beat the relevant indices.

I think in euros. Why bonds in dollars too?

Because some of the most solid companies issue bonds in dollars, often with a higher coupon. You decide how large the dollar share in your portfolio may be. We show you what it earns and what currency risk it carries.

Why are the performance figures in euros?

Because most of our investments are denominated in euros and the performance report is audited by BDO in euros. For a euro portfolio the figures are therefore directly comparable.

Where is my money?

In an account and portfolio in your name at a custodian bank of your choice: Swissquote, Bank J. Safra Sarasin, Liechtensteinische Landesbank or, from January 2027, V-Bank. Genève Invest has negotiated terms with these banks that you would normally not receive as an individual client. We receive a management power of attorney for investment decisions, but no access to withdrawals.

Can I terminate?

Yes, at the end of each quarter, with no minimum term. Your portfolio remains; you decide what happens to it.

From what amount do you work with clients?

From investable assets of €100,000. Below that we recommend the documents in our library.

Who supervises Genève Invest?

Genève Invest Sàrl is licensed by FINMA as an asset manager. Ongoing supervision is carried out by the supervisory organisation OSFINcontrol AG.

Are my returns guaranteed?

No. Bonds and equities are subject to price, credit and currency risks. What we offer is transparency: you can see at any time what your portfolio is doing and what it costs.

What is Plan 95?

A free package in two parts: the leverage calculation showing the return your capital needs to last to 95, and a 30-minute conversation with an adviser in your language. It is for people with investable assets from €100,000.

What is in the market outlook?

Our assessment for the second half of 2026 on 32 pages: rates, bonds, equities, currencies and commodities, three scenarios rather than a single forecast, and clear positions on where we buy, sell or wait. It is an assessment, not a commitment, and recommends no individual securities.

What is the portfolio review?

You send us your current portfolio statement, we examine risk, costs, quality of positions and gaps, and show you in writing and in a conversation what is costing you return. Free, for portfolios from €100,000. Whether you change anything afterwards is your decision.
Genève Invest in numbers
2002Founded in Geneva, owner-managed ever since
4Languages with a dedicated contact: German, French, Italian, English
4Custodian banks to choose from: Swissquote, Safra Sarasin, LLB, V-Bank
100,000euros minimum investment
0%performance fee as long as your portfolio is below its previous high (high-water mark)
QuarterTermination at any quarter end, no minimum term
Genève Invest in 60 seconds

Genève Invest Sàrl is an independent, FINMA-licensed asset manager based in Geneva, founded in 2002. The company manages the assets of private individuals with investable assets from €100,000, individually and in individual securities, with a focus on retirement: carefully selected corporate bonds in euros and dollars paying up to 8 percent and European and international quality equities on value principles. The goal is a systematic outperformance of the relevant indices. Clients hold account and portfolio in their own name at Swissquote, Bank J. Safra Sarasin, Liechtensteinische Landesbank or, from 2027, V-Bank, at preferential terms; Genève Invest acts under a management power of attorney. Four strategy groups pool similar mandates; their performance is published, calculated in euros and audited by BDO. Remuneration consists of a small, transparent base fee and a results-based performance fee with high-water mark; mandates can be terminated at the end of each quarter. Supervision is carried out by OSFINcontrol AG.